All Categories
Featured
The Financial Impact of Ethical Supply Chains
Table of Contents
For customers, it's a "great time to be deploying capital into these markets," due to the fact that the mid- to late-stage companies have "a lot more practical assessments" than start-ups, Cohen said."We can in fact also buy shares of companies from early-stage financiers who are aiming to exit their position," he said. "We can type of been available in, swoop in and purchase them at a discount." Aaron White is the chief growth officer and a principal of Bay Area, California-based Adero Partners.
Since business are much more important by the time they do go public or get acquired by other companies, some financiers have the chance to enjoy big returns in areas like SaaS that "have lower overhead and more rapid development as they broaden the item that they have and raise awareness," he said."The private markets have established to the point that business no longer require to have an IPO to raise capital," White stated.
With fewer publicly traded companies and a growing personal credit market, equity capital investments in the center to late rounds of funding have become a far more unique property class. Processing ContentMid- to late-stage equity capital funds bring much stabler returns and lower failure rates with the possibility of faster liquidity events than investments in startup companies.
Global Expansion Roadmaps for British Leaders in 2026
As wealth management companies flock into personal capital and other nonpublic alternative investments, one registered financial investment advisory its 2nd mid- to late-stage venture fund this month with an objective of raising $50 million and retail-client-catered financial investment minimums of $250,000. New York-based is pitching its to the high net worth clients of fellow RIAs since the "$2 million and $3 million customer" often has trouble qualifying or paying the charges for those kinds of personal market investments, CEO Sevasti Balafas said in an interview.
Sevasti Balafas is the founder and CEO of New York-based registered financial investment advisory firm GoalVest Advisory. GoalVest Advisory and venture funds in specific have proven in terms of their returns and, as well as being a location of innovation, and themselves.
The "liquidity timeline" and "risk-return profile" for mid- to late-stage investments look much various from startups that can have lockup durations for "a prolonged number of years" as companies remain personal for a lot longer these days, according to Kaidi Gao, an associate venture capital research study analyst at data and research firm, a Morningstar business.
"In contrast, later-stage financial investments are more secure, due to the fact that at this moment, companies have actually currently evaluated out their products and services, and are focusing on scaling and development. Compared to their early-stage equivalents, later-stage start-ups have fairly lower threat of failure. Multiples generated from financial investments made to fully grown organizations tend to be stabler, however you are much less most likely to see outsized returns there."Certified financiers are gaining more ways to purchase mid- to late-stage companies through expanding types of products such as interval funds that have lower management fees and carried-interest profit-sharing requirements, a much shorter liquidity timeline and diversified holdings, according to Aaron White, the primary development officer of Bay Location, California-based.
Analyzing ESG Finance Mandates for UK Firms
Between those two classifications, they remain in the mid- to late-stage. "The company is attempting to broaden their reach, their consumer base, ramp up sales and marketing and move into profitability at some point in the future," White said. "Those are the 3 stages that we take a look at purchasing, and there are the advantages and disadvantages of each."The GoalVest item charges a management charge of 1.5% and carried-interest sharing of 15%, compared to the particular conventional market rates of 2% and 20%, and it will purchase a similar group of companies to that of the first fund's approximately 20 holdings that include pastry shop chain Sleeping disorders Cookies, defense innovation firm Shield AI and sales software, according to Balafas and Blair Cohen, the head of private investments with.
For customers, it's a "excellent time to be releasing capital into these markets," due to the fact that the mid- to late-stage companies have "a lot more realistic valuations" than startups, Cohen stated."We can actually also purchase shares of companies from early-stage financiers who are looking to leave their position," he said.
Mid-stage startups are operating in a really various venture capital landscape in 2026. It's not that financing has actually disappeared, however the expectations around it have evolved. Financiers can be slower to devote, more selective about where dollars go, and focused on real traction over momentum. For founders, this indicates the bar has been raised.
Rather, expectations are now centered around capital efficiency, sustainability, and strategic positioning. Adding to the intricacy, local communities are diverging, and funding outcomes are significantly shaped by sector expertise and regional characteristics. Here's how today's mid-stage startups are adjusting, and what creators may wish to bear in mind to stay fundraising-ready in a slower-moving, but still active, market.
In 2021 and 2022, "development at all costs" was the norm. Creators raised big rounds at sky-high valuations. As economic conditions shifted, numerous of those boom-era deals are now underwater-- and financier habits has actually changed in kind. Expectations shifted far from speed and scale and toward operational resilience.
How Mid-Market Firms Drive Digital Transformation
The average time to close a VC round hit approximately 2 years, up from about 1.3-1.4 years in 2019. Investors became more selective, looking for startups with strong cash flow, solid system economics, and the ability to do more with less. For mid-stage start-ups, this shift might mean basics come initially.
While offers are still taking place, they're taking longer, and the bar to follow-on funding has risen a shift we explored in our breakdown of three essential fundraising trends to enjoy. For mid-stage start-ups, the implication can be clear: momentum alone won't always cut it. Investors desire to see a clear focus on the principles, consisting of: Capital performance: Doing more with less Runway management: Having sufficient cash to remain flexible, particularly offered today's prolonged fundraising timelines Functional rigor: Clear metrics, lean teams, and smart invest Startups with inflated appraisals can now be under greater pressure to prove traction and validate their rates.
With average fundraising timelines now extending to roughly two years, capital has been flowing towards startups with solid principles and long lasting competitive benefits-- not simply growth stories.
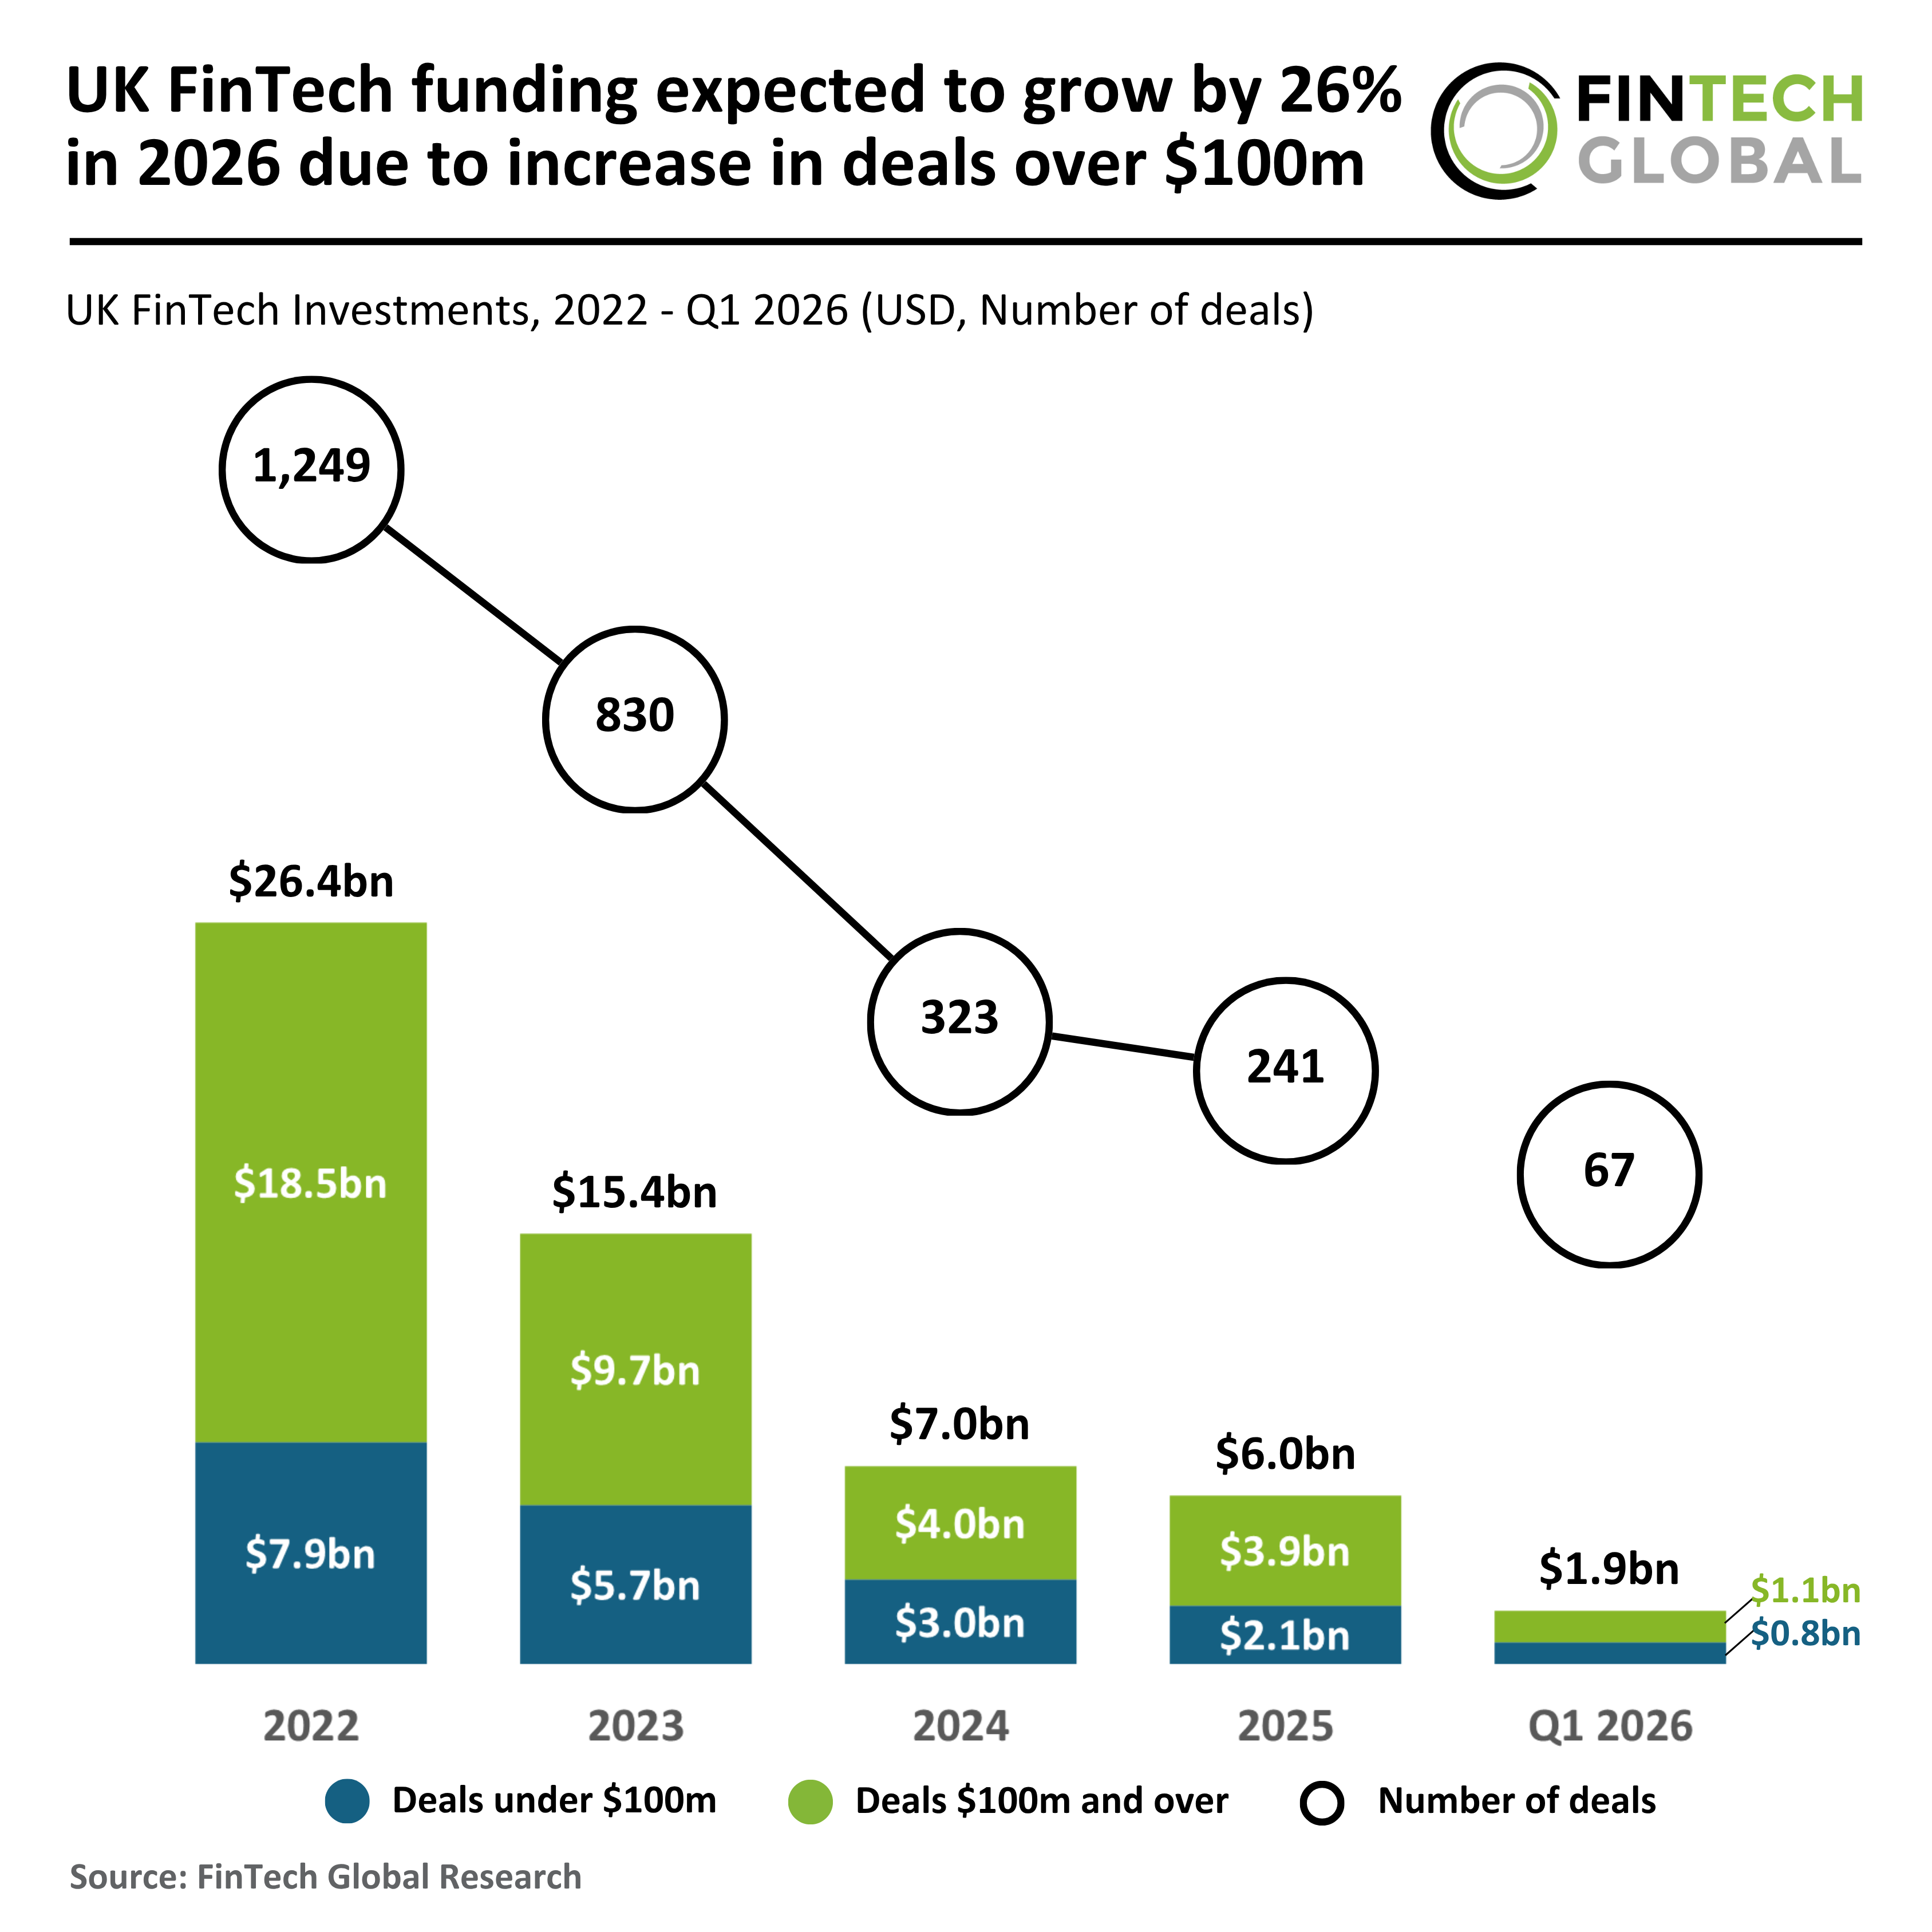
Start-ups deal with a moving set of expectations and an endeavor capital landscape that's progressively varied. Pulling from our Equity Capital Report in cooperation with Pitchbook, in 2026, 5 crucial patterns are forming where capital flows and the length of time it may require to raise: AI represented almost half of all United States VC deal worth and nearly a third of deal count in 2024.

Latest Posts

Essential Corporate Scaling Advice in 2026
Unlocking VC and Mid-Market Enterprise Growth
The Financial Impact of Ethical Supply Chains